Category: Uncategorized

  • SAP Cloud Platform Integration Architecture and Components

    SAP Cloud Platform Integration Architecture and Components

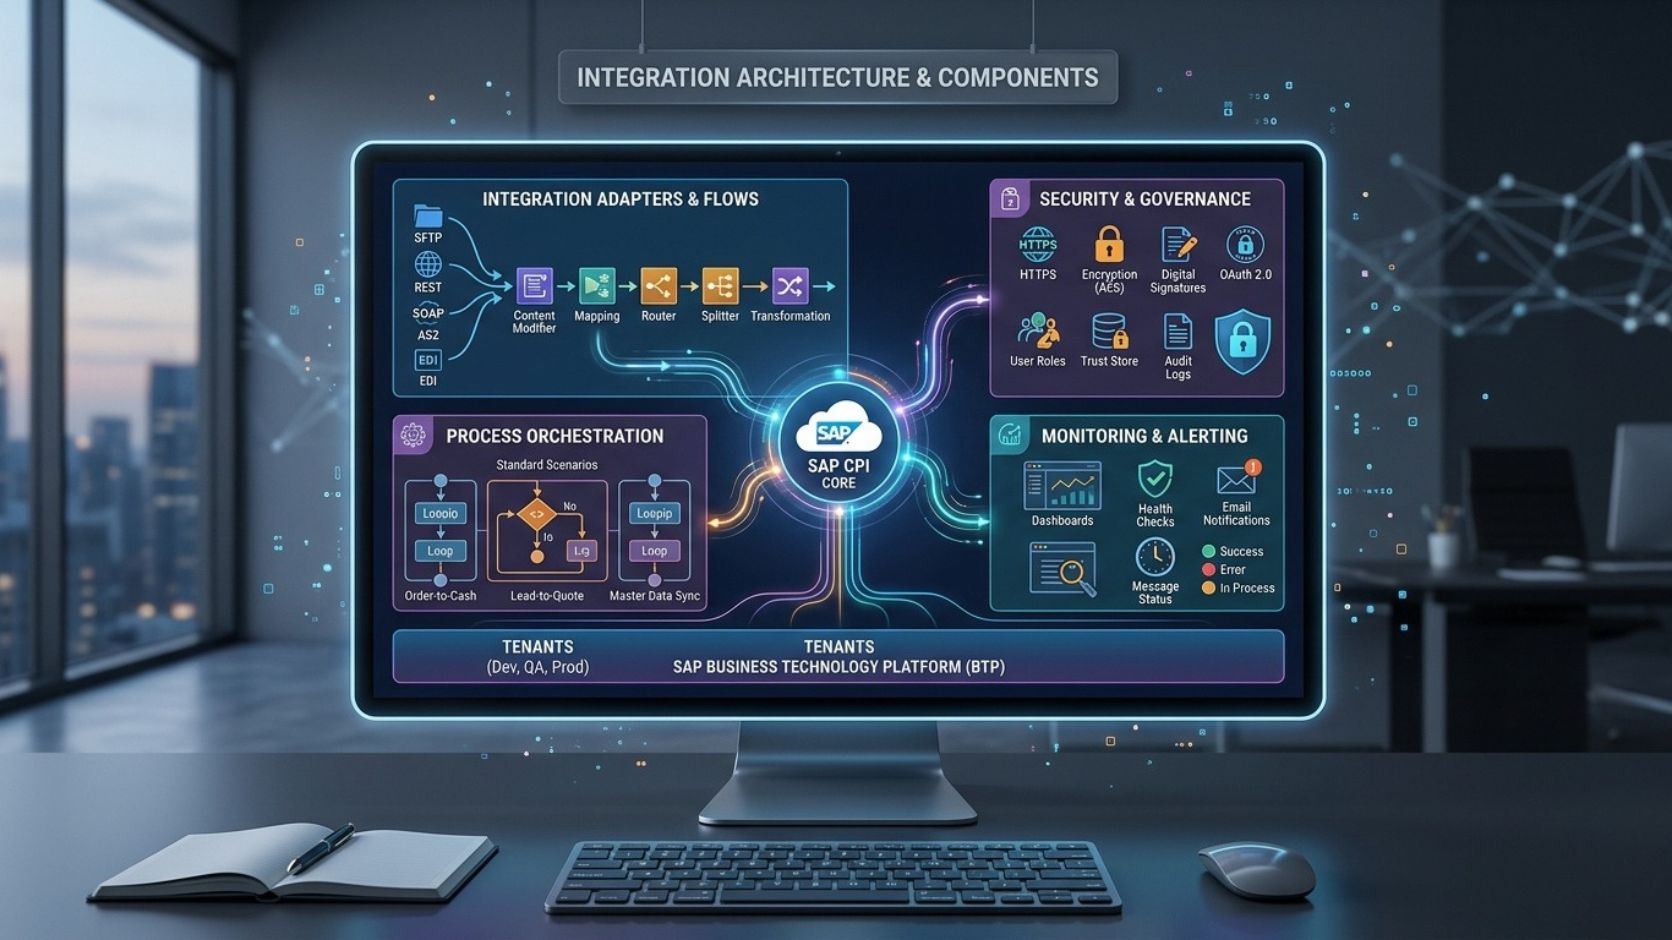
    SAP Cloud Platform Integration provides a cloud-based architecture for connecting SAP applications, non-SAP systems, APIs, databases, and external services. It provides the tools required to receive, process, transform, route, monitor, and deliver business data between connected systems.

    SAP Cloud Platform Integration is commonly called SAP CPI. It is now part of SAP Integration Suite, where the integration capability is known as Cloud Integration. Its architecture supports different integration patterns, communication protocols, data formats, authentication methods, and deployment models.

    Understanding the architecture is important for developers, integration consultants, administrators, and organizations planning SAP integration projects. The main concepts include integration flows, sender and receiver systems, adapters, message processing, mappings, security, monitoring, runtime components, and Destinations.

    What Is SAP Cloud Platform Integration Architecture?

    SAP Cloud Platform Integration architecture defines how applications communicate through the integration platform.

    A basic architecture contains three major areas: the source system, the integration layer, and the target system.

    Source System → SAP Cloud Platform Integration → Target System

    The source system sends information to SAP Cloud Platform Integration. The platform processes the message according to the configured integration flow. The processed message is then delivered to the target system.

    For example, SAP S/4HANA can send an order to an external logistics application. The integration platform can receive the message, validate the information, transform the data structure, and send it to the logistics system.

    The architecture can also support more complex scenarios involving multiple systems and processing steps.

    SAP Cloud Platform Integration Architecture Overview

    A typical SAP Cloud Platform Integration architecture contains several logical layers.

    The sender layer contains applications that initiate communication. These can include SAP S/4HANA, SAP SuccessFactors, Salesforce, custom applications, databases, or external APIs.

    The integration layer contains integration flows and processing components. This is where messages are transformed, routed, validated, filtered, and processed.

    The receiver layer contains systems that receive the processed information.

    Connectivity components such as adapters provide communication between these systems and the integration runtime.

    A simplified architecture can be represented as:

    Sender → Sender Adapter → Integration Flow → Processing → Receiver Adapter → Receiver

    The exact architecture depends on the integration scenario.

    Main Components of SAP Cloud Platform Integration

    SAP Cloud Platform Integration contains several components that work together.

    The integration flow defines the processing logic.

    The adapter provides communication with the source or target system.

    The message processing components transform and control the message.

    The integration runtime executes the integration flow.

    The security configuration controls authentication and secure communication.

    The monitoring capabilities provide information about message processing.

    Destinations can provide connection information for applications and services that need to communicate with other systems.

    These components form the technical foundation of an integration scenario.

    Integration Flows

    Integration flows, commonly called iFlows, are one of the main components of SAP Cloud Platform Integration.

    An integration flow defines how a message moves through the integration platform.

    A flow can start with a sender adapter. The message then passes through different processing steps. The flow ends with a receiver adapter that delivers the message to the target system.

    For example:

    SAP S/4HANA → IDoc Adapter → Mapping → Router → HTTP Adapter → External Application

    Each component performs a specific function.

    An integration flow can contain mapping, routing, filtering, content modification, conversion, scripting, validation, and exception handling.

    This allows developers to create integration logic without building a separate custom application for every connection.

    Sender and Receiver Systems

    The sender is the system that starts the communication.

    A sender can be an SAP application, third-party platform, web application, API client, or another integration process.

    The receiver is the system that receives the processed message.

    One integration flow can have one or more receiver scenarios depending on the architecture.

    For example, an order from SAP S/4HANA could be sent to an external warehouse system and a reporting platform. A router can determine which receiver should receive specific information.

    The sender and receiver configuration depends on the communication protocol and authentication requirements.

    Adapters in SAP Cloud Platform Integration

    Adapters connect integration flows to external systems.

    Different applications use different protocols. Adapters provide the required communication mechanism.

    Common adapter types include HTTP, SOAP, OData, SFTP, IDoc, and ProcessDirect.

    The HTTP adapter can communicate with HTTP-based services and REST APIs. The SOAP adapter is used for SOAP web services. The SFTP adapter supports secure file-based communication.

    The IDoc adapter supports SAP IDoc-based integration scenarios.

    The OData adapter can communicate with OData services.

    Choosing the correct adapter depends on the capabilities of the source or target system.

    Integration Runtime

    The integration runtime is responsible for executing integration flows.

    After an integration flow is deployed, the runtime processes messages according to the configured logic.

    For example, when an incoming request reaches an integration endpoint, the runtime can receive the message, execute mapping, apply routing conditions, call a receiver system, and process the response.

    The runtime therefore provides the execution environment for integration processes.

    Performance and processing requirements depend on message size, message volume, transformation complexity, network conditions, and the connected systems.

    Message Processing

    Message processing is the central activity inside an integration flow.

    A message can contain business information such as customer data, sales orders, invoices, employee records, or product information.

    The integration process can modify the message before sending it to the target system.

    For example, a source system may provide customer information in XML:

    <CustomerID>1001</CustomerID>

    The target system may require a JSON structure with a different field name.

    The integration flow can transform the message into the required structure.

    Processing can also include validation, filtering, routing, enrichment, and conversion.

    Message Mapping

    Message mapping is used when source and target systems use different data structures.

    For example, the source system may use:

    Customer_ID

    while the target system expects:

    CustomerNumber

    A mapping connects the source field with the corresponding target field.

    Mapping can also perform transformations such as combining multiple fields, changing data types, applying conditions, and converting values.

    SAP Cloud Platform Integration provides graphical mapping capabilities. Developers can also use other transformation methods when the integration scenario requires additional processing.

    Routing and Content-Based Processing

    Routing determines where a message should go based on defined conditions.

    For example, an integration flow may receive orders from multiple countries. A router can send European orders to one processing path and North American orders to another.

    Routing can also be based on message fields, headers, properties, or other conditions.

    This allows a single integration flow to handle different business scenarios.

    Content-based routing is useful when different data values require different processing logic.

    Security Architecture

    Security is an important component of SAP Cloud Platform Integration architecture.

    The platform supports different authentication and authorization mechanisms depending on the integration scenario.

    These can include OAuth, basic authentication, client certificates, and other supported security methods.

    HTTPS can provide encrypted communication between systems.

    Security configuration can also control access to integration endpoints and external resources.

    Credentials should be managed through appropriate secure configuration mechanisms. Sensitive authentication information should not be unnecessarily embedded in integration scripts or message content.

    The Role of Destinations

    Destinations provide connection information that applications and services can use to access target systems.

    A Destination can include information such as a target URL, authentication configuration, and other connection properties.

    For example, an application may need to communicate with an external API. Instead of storing connection information directly inside application logic, the application can use a configured Destination.

    Destinations can therefore separate connection configuration from application logic.

    This can be useful when the same application needs to communicate with different systems across development, testing, and production environments.

    The exact properties of Destinations depend on the target service and authentication method.

    In an SAP cloud architecture, Destinations can also support standardized connectivity between applications and services.

    APIs and Connectivity

    APIs are another important part of SAP integration architecture.

    An API provides a defined interface that allows one application to communicate with another application.

    REST APIs commonly use HTTP methods such as GET, POST, PUT, and DELETE. Data is frequently exchanged using JSON.

    SOAP services use XML-based messages and established web service standards.

    SAP Cloud Platform Integration can consume and process API requests depending on the integration architecture.

    For example:

    External Application → REST API → Integration Flow → SAP S/4HANA API

    The integration flow can validate and transform the incoming request before calling the SAP API.

    Cloud-to-Cloud Architecture

    Cloud-to-cloud integration connects applications operating in cloud environments.

    An organization may use SAP S/4HANA Cloud, SAP SuccessFactors, Salesforce, and an external logistics platform.

    Each application may have different APIs and data formats.

    SAP Cloud Platform Integration can act as the central integration layer.

    For example:

    SAP SuccessFactors → Cloud Integration → External HR Platform

    The integration flow receives employee information, processes the data, transforms the structure, and sends it to the external system.

    This architecture supports centralized integration management across multiple cloud services.

    Hybrid Integration Architecture

    Many organizations use both cloud and on-premises systems.

    For example, SAP S/4HANA or another SAP system may operate in an on-premises environment while a CRM application operates in the cloud.

    A hybrid integration architecture connects these environments.

    SAP Cloud Platform Integration can provide the cloud integration layer, while secure connectivity mechanisms connect cloud services with on-premises systems.

    The architecture must consider network connectivity, authentication, firewall rules, certificates, data protection, and system availability.

    Monitoring Architecture

    Monitoring provides visibility into integration processing.

    Administrators can inspect message processing and identify successful or failed messages.

    Monitoring can help identify problems such as:

    • Authentication failures
    • Invalid message structures
    • Mapping errors
    • Unavailable endpoints
    • Network problems
    • Target-system errors

    The exact monitoring information depends on the integration scenario and configured logging.

    Monitoring is important because integration failures can affect multiple business processes.

    Error Handling Architecture

    Integration flows can include error-handling logic.

    When a message fails, an exception subprocess can capture the error and execute a defined process.

    For example, a failed message can be logged, sent to a separate error process, or handled according to a defined business rule.

    Error handling should account for technical failures and business validation failures.

    Technical failures may include connection problems or authentication errors. Business failures may occur when required information is missing or invalid.

    Development, Testing, and Production

    SAP Cloud Platform Integration projects commonly require separate environments for development, testing, and production.

    The development environment is used to create and modify integration flows.

    The testing environment is used to validate integration behavior before production deployment.

    The production environment handles live business transactions.

    Connection settings may differ between environments. Destinations can be useful when connection information needs to be configured according to the environment.

    For example, a development system may use a test API endpoint while production uses a live endpoint.

    Separating these environments reduces the risk of testing changes directly against live business systems.

    SAP Cloud Platform Integration Architecture for S/4HANA

    SAP S/4HANA can participate in integration scenarios using APIs, IDocs, OData services, and other supported technologies.

    For example, an order can originate in an external application and be sent to SAP S/4HANA.

    The integration architecture may look like:

    E-Commerce Platform → REST API → Cloud Integration → Mapping → S/4HANA API

    The integration flow can validate the order, transform the data, and send it to S/4HANA.

    The exact architecture depends on the available interfaces and business requirements.

    SAP Cloud Platform Integration Architecture for Third-Party Systems

    Third-party applications can also be connected through SAP Cloud Platform Integration.

    Examples include CRM systems, payment platforms, logistics applications, e-commerce platforms, marketing systems, and analytics tools.

    A third-party application can send information through an API or file interface. SAP Cloud Platform Integration can process that information and send it to an SAP application.

    This provides a structured integration layer between different technology platforms.

    Common Architecture Patterns

    SAP Cloud Platform Integration can support several common integration patterns.

    Point-to-point integration connects two systems through a defined integration flow.

    Request-response integration allows a sender to request information and receive a response.

    Asynchronous integration allows messages to be processed without requiring an immediate response.

    Scheduled integration processes information at defined times or intervals.

    File-based integration exchanges information through files, commonly using SFTP.

    The appropriate architecture depends on the business process, data volume, response requirements, security, and capabilities of the connected systems.

    How the Components Work Together

    The components of SAP Cloud Platform Integration are designed to work as a complete processing architecture.

    A sender system initiates communication. The sender adapter receives the message. The integration runtime executes the integration flow.

    Processing components transform and validate the message. A router can determine the correct processing path. A receiver adapter then communicates with the target system.

    Security controls authentication and secure communication. Monitoring provides visibility into message processing.

    Destinations can provide reusable connection information for supported application and service scenarios.

    Together, these components provide the technical structure required for enterprise integration.

    Frequently Asked Questions

    What is SAP Cloud Platform Integration architecture?

    SAP Cloud Platform Integration architecture defines how source systems, integration flows, adapters, processing components, security services, and target systems work together to exchange business information.

    What are the main components of SAP Cloud Platform Integration?

    The main components include integration flows, adapters, integration runtime, message processing components, mappings, routing, security, monitoring, and connectivity configuration.

    What are Destinations in SAP Cloud Platform Integration?

    Destinations provide connection information used by applications and services to communicate with target systems. They can include URLs, authentication settings, and other connection properties.

    Why are adapters important?

    Adapters provide communication between the integration platform and external systems. They support different protocols and technologies, including HTTP, SOAP, SFTP, OData, and IDoc.

    What is an integration runtime?

    The integration runtime executes deployed integration flows. It receives messages, processes integration logic, performs transformations, and communicates with target systems.

    How does message mapping work?

    Message mapping connects fields and structures from a source message to the format required by a target system. It can also transform values and data types.

    Can SAP Cloud Platform Integration connect cloud and on-premises systems?

    Yes. It can participate in hybrid integration architectures that connect cloud applications with on-premises SAP and non-SAP systems.

    How does SAP Cloud Platform Integration handle security?

    It supports multiple authentication and secure communication methods. The exact configuration depends on the connected systems and integration requirements.

    Why are Destinations useful?

    Destinations can separate connection information from application logic. This can make environment-specific connection management easier across development, testing, and production.

    Conclusion

    SAP Cloud Platform Integration architecture provides a structured framework for connecting SAP applications, third-party systems, APIs, and cloud services. Its architecture includes integration flows, adapters, runtime processing, message mapping, routing, security, monitoring, and error handling.

    The integration flow defines how information moves through the platform. Adapters provide connectivity, while processing components transform and control the message. APIs support application communication, and monitoring provides visibility into integration activity.

    Destinations are also an important part of SAP cloud connectivity because they can provide reusable connection information for applications and services.

    A clear understanding of these components helps organizations design integration architectures for SAP S/4HANA, SAP SuccessFactors, cloud applications, APIs, and third-party systems. SAP Cloud Platform Integration, now part of SAP Integration Suite, provides the integration capabilities required to manage these connected business environments.
  • White-Label Card Programs vs. API-First Issuing: Which Fits Your Business?

    White-Label Card Programs vs. API-First Issuing: Which Fits Your Business?

    Choosing between white-label card programs and API-first issuing depends on how a business balances speed, control, and operational responsibility. White-label models simplify launch and reduce compliance strain, while API-first platforms offer deeper customization and stronger long-term flexibility. The tradeoff is rarely just technical. It shapes cost, scalability, and customer experience. The more important question is not which model is better, but which one fits the business it must support.

    What Are White-Label Card Programs?

    At a high level, white-label card programs are prebuilt card-issuing solutions that a provider develops, operates, and licenses to other companies under those companies’ own brands. They typically include network relationships, compliance oversight, processing infrastructure, and standard cardholder features, allowing businesses to launch branded payment products without building an issuing stack internally.

    From an operational perspective, the model reduces implementation complexity, accelerates time to market, and shifts much of the regulatory and technical burden to the program manager or issuer.

    From a commercial perspective, it supports differentiated branding strategies by letting companies present cards as native extensions of their customer experience. This structure can strengthen market positioning, especially for firms seeking faster entry, predictable costs, and controlled customization within predefined program parameters and service levels.

    What Is API-First Issuing?

    By contrast, API-first issuing refers to a card issuance model built around programmable interfaces that allow businesses to embed card creation, funding controls, transaction monitoring, and lifecycle management directly into their own products and workflows.

    • API benefits include automation and faster deployment.
    • Integration challenges depend on legacy systems.
    • Customization options support tailored controls and features.
    • Scalability factors affect volume handling and expansion.
    • Compliance considerations shape oversight, security, and reporting.

    This model emphasizes developer control, modular architecture, and direct orchestration of issuing functions.

    It can improve user experience by enabling embedded, seamless payment interactions.

    Market trends favor flexible infrastructure that adapts quickly to product changes and regional requirements.

    Cost implications vary with engineering resources, vendor pricing, and ongoing operational complexity.

    How to Compare White-Label vs. API-First Issuing

    A practical comparison between white-label card programs and API-first issuing starts with launch speed, since time to market often shapes early economics and execution risk.

    It then turns to integration depth and operational control, where the tradeoff is typically between faster deployment and greater flexibility.

    This framework clarifies which model better fits a company’s technical capacity, product goals, and compliance posture.

    Launch Speed Comparison

    Because launch speed is often treated as a proxy for program viability, the comparison between white-label card programs and API-first issuing should separate initial go-live timelines from the work required to reach the desired level of customization, compliance readiness, and operational control.

    White-label models usually accelerate market readiness by packaging core capabilities and predefined launch strategies. API-first issuing may appear slower at first, yet timelines depend heavily on scope, jurisdiction, and internal resourcing.

    • White-label programs often shorten vendor selection cycles
    • Prebuilt workflows can compress testing and approval windows
    • API-first timelines vary with product complexity
    • Regulatory preparation can delay both models significantly
    • Speed should be measured against launch objectives

    A faster start is not automatically a better launch. The relevant benchmark is time to a viable, compliant, commercially usable card program.

    Integration And Control

    Consider integration and control together, since the practical difference between white-label card programs and API-first issuing lies less in feature availability than in who defines system behavior, data flows, and operational dependencies.

    White-label models typically offer faster deployment because core workflows, compliance processes, and reporting structures arrive prebuilt. Those integration benefits reduce engineering demands but constrain customization, partner selection, and sequencing across internal systems.

    API-first issuing reverses that tradeoff. It gives businesses deeper authority over ledger design, authorization logic, event handling, and customer experience, allowing card functionality to align with existing architecture rather than forcing adaptation to a vendor framework.

    However, greater flexibility introduces control challenges: more technical ownership, more dependency management, and stricter requirements for governance, observability, security, and change coordination across product, compliance, and operations teams.

    Reducing Sign-Up Friction Without Cutting Corners

    Every abandoned onboarding flow is a lost customer, and modern card platforms have responded by streamlining sign-up — letting users start with an email and complete verification steps progressively as their usage grows. This pattern has proven especially effective in high-growth markets: platforms offering a virtual card API in Nigeria have shown that reducing upfront friction, while maintaining proper verification, dramatically improves activation rates.

    White-Label vs. API-First Issuing: Key Differences

    While both models enable companies to launch payment cards, they differ fundamentally in control, speed, and technical ownership.

    White-label programs package infrastructure, compliance, and user workflows into a managed offering, emphasizing white label benefits such as reduced operational burden and standardized deployment.

    API-first issuing exposes card creation, controls, and ledger functions through developer interfaces, highlighting api first advantages in flexibility, customization, and system interoperability.

    • White-label prioritizes managed service and predefined configurations
    • API-first prioritizes modular architecture and direct integration
    • White-label limits deep product tailoring for simplicity
    • API-first requires stronger internal engineering and product governance
    • Both models support branded card experiences under different operating models

    The core distinction lies in whether a business values vendor-managed orchestration or platform-level programmability across its card stack and risk controls.

    White-Label or API-First: Which Launches Faster?

    Launch speed is typically determined by two variables: deployment timeline and integration complexity.

    White-label programs often reach market sooner because core infrastructure, compliance controls, and user flows are already in place.

    API-first issuing can require a longer path to launch, as greater customization usually increases engineering effort, testing scope, and system integration demands.

    Deployment Timeline

    Although deployment speed is often framed as a simple race, the faster path depends on how much control the program requires at launch.

    White-label programs usually compress early timelines because core workflows, compliance structures, and operational processes already exist.

    API-first issuing may appear slower initially, yet it can better match long-term product goals when customization matters.

    Accurate timeline estimation depends on internal decision speed, vendor readiness, and approval sequencing, not just technical ambition alone.

    • White-label reduces initial setup time
    • API-first extends planning before launch
    • Governance delays often outweigh build speed
    • Vendor dependencies shape deployment challenges
    • Custom requirements can reset schedules

    For firms prioritizing market entry, white-label often reaches production sooner.

    For firms prioritizing differentiated capabilities, API-first timelines may be justified despite longer pre-launch coordination and broader approval milestones overall.

    Integration Complexity

    Integration complexity often determines whether a program reaches production on schedule, because technical effort extends beyond card issuance into ledger connectivity, authentication, reporting, fraud controls, customer support workflows, and downstream finance systems.

    White-label platforms usually reduce integration scope by bundling core capabilities, predefined interfaces, and compliance tooling, which can accelerate implementation for teams with limited engineering capacity.

    API-first issuing offers greater flexibility but shifts orchestration responsibilities to the business. Teams must connect payment rails, KYC, general ledger logic, dispute handling, notifications, and analytics while preserving reliability and user experience.

    That architecture can produce stronger differentiation, yet it lengthens testing cycles and increases dependency management. Launch speed therefore depends less on issuance alone than on internal technical maturity, available technical support, and tolerance for iterative integration risk across vendors and systems.

    Which Gives You More Product Control?

    Where product control matters most, the distinction is usually straightforward: API-first issuing gives program managers far greater authority over card logic, user flows, ledger behavior, controls, and data exposure than a white-label card program.

    • Greater product flexibility
    • Stronger brand identity
    • Tailored customer experience
    • Faster feature enhancements
    • Clearer market differentiation

    White-label models accelerate launch, but they confine teams to predefined workflows, interfaces, and release priorities. That limits user engagement, constrains experimentation, and weakens competitive advantage when differentiation depends on embedded financial features.

    API-first issuing supports a more deliberate long term strategy because product teams can shape experiences around specific customer segments, operational models, and evolving business goals. The result is tighter alignment between the card program and broader platform economics, making customization a core lever for retention, relevance, and sustained growth over time.

    Who Handles Compliance and Risk?

    Control over the product does not remove responsibility for operating it safely, and this is the point at which white-label and API-first models separate just as clearly.

    In white-label programs, the provider typically carries most Compliance management duties, including meeting Regulatory requirements, running Compliance audits, maintaining Data security controls, and supporting Fraud prevention frameworks.

    API-first issuing shifts far more accountability to the business. The platform may supply tools, but Risk assessment, policy design, transaction monitoring, and parts of Financial oversight often remain with the client or its regulated partners.

    That increases operational exposure and narrows Liability protection if controls are weak. The practical distinction is not whether compliance exists in either model, but who owns execution, evidence, and remediation when regulators, networks, or banking partners question program performance or customer outcomes.

    How Much Integration Work Is Required?

    Compare the technical lift, and the difference becomes immediate. White-label card programs usually arrive with prebuilt workflows, hosted dashboards, and standard user journeys, reducing custom development.

    API-first issuing demands deeper engineering involvement because controls, ledger logic, onboarding flows, and reporting layers must be assembled around the provider’s endpoints. As a result, integration timeframes differ sharply, as do required technical resources.

    • White-label setups favor faster implementation.
    • API-first models require stronger internal engineering.
    • Hosted components limit front-end customization needs.
    • Custom architectures increase testing and deployment complexity.
    • Ongoing maintenance remains heavier in API-first environments.

    The practical distinction is control versus speed.

    Businesses prioritizing launch efficiency often prefer white-label structures, while product-led teams with mature technical resources may accept longer integration timeframes to gain more configurability, ownership, and product differentiation over time.

    What Do White-Label Card Programs Cost?

    Pricing in white-label card programs typically centers on packaged platform fees rather than purely usage-based infrastructure costs. Vendors often bundle program management, compliance support, processor connectivity, BIN sponsorship, and dashboard access into recurring monthly or annual charges.

    Setup fees are also common, especially when branding, card design, and approval workflows require configuration.

    Additional cost factors usually include card manufacturing, shipping, transaction processing, funding flows, dispute handling, and customer support. Some providers impose minimums, implementation fees, or tiered pricing models tied to active cards, transaction volume, or service levels.

    Revenue-sharing arrangements may offset certain expenses, but they can also reduce margin predictability. Overall, white-label economics tend to favor businesses seeking faster launch and operational simplicity, while accepting less granular control over how individual services are priced and negotiated.

    When Does API-First Issuing Scale Better?

    API-first issuing tends to scale better when transaction volume rises beyond the operational limits of templated program structures.

    It also becomes more advantageous when a business requires deeper product customization, including tailored controls, workflows, and ledger logic.

    In these cases, the model offers greater flexibility and long-term efficiency, though with higher implementation responsibility.

    High-Volume Program Growth

    As transaction volumes climb, the scalability advantage of API-first issuing typically emerges when a program requires frequent product changes, granular controls, or integrations across multiple systems and geographies.

    At scale, operational efficiency depends on high volume scalability, resilient orchestration, and disciplined volume management without excessive manual intervention or vendor bottlenecks.

    • Faster adaptation to shifting transaction patterns
    • Centralized controls across processors and regions
    • Automation for funding, ledgering, and reconciliation
    • Better monitoring for authorization and decline trends
    • More reliable support for parallel market expansion

    White-label programs can absorb moderate growth efficiently, but API-first models often outperform when throughput, workflow complexity, and reporting demands rise simultaneously.

    Their advantage is less about features than about sustaining speed, consistency, and governance under increasing operational load.

    Deeper Product Customization

    Complexity becomes the clearest dividing line when a card program needs deeper product customization across spend controls, funding logic, user journeys, and partner-specific rules. At that point, API-first issuing typically scales better because it supports configurable workflows rather than fixed templates.

    Teams can tailor authorization parameters, ledger behavior, real-time notifications, and embedded compliance checks to match distinct operating models.

    White-label programs may still offer speed, but they often constrain differentiation once requirements multiply. API-first infrastructure enables custom branding options, granular controls, and direct orchestration with internal systems, creating stronger alignment between the card product and the underlying business process.

    That flexibility also supports user experience enhancement, since interfaces, funding paths, and approval logic can be refined continuously without waiting for platform-level roadmap changes or vendor reprioritization.

    When Should You Choose Each Model?

    When each model makes sense depends on the company’s product goals, regulatory appetite, internal technical capacity, and speed-to-market requirements.

    White-label programs suit firms prioritizing launch efficiency, predictable compliance support, and straightforward alignment with business objectives and target audience needs.

    • Choose white-label for rapid deployment
    • Use it for lower operational complexity
    • Favor it when customization is limited

    API-first issuing fits companies that view card infrastructure as a core product layer.

    It is better for teams with engineering resources, complex workflows, and long-term plans for embedded finance innovation.

    Where flexibility, ownership, and tailored user experiences drive competitive advantage, API-first usually delivers stronger strategic value.

    The correct choice follows operating model, growth horizon, and risk tolerance.

    Frequently Asked Questions

    Can You Migrate From White-Label to Api-First Later?

    Yes, migration from white-label to API-first is possible later, but organizations should expect migration challenges, compliance remapping, and operational redesign. Success depends on clear architecture planning, vendor cooperation, and realistic integration timelines aligned with product priorities.

    How Do Cardholder Dispute Workflows Differ Between Both Models?

    The theory largely holds: dispute workflows differ significantly. White-label programs centralize Dispute resolution and Customer support through providers, improving Workflow efficiency but limiting control; API-first issuing internalizes Fraud management, customization, and operational responsibility for investigations.

    What Customization Options Exist for Virtual and Tokenized Cards?

    Customization options for virtual and tokenized cards include controls over branding strategies, card art, spend limits, merchant categories, lifecycle rules, wallet provisioning, and authentication flows; flexibility varies by model, shaping integration depth, compliance scope, and user experience.

    How Do International Expansion Needs Affect the Best Issuing Model?

    Rapid entry favors white-label programs; complex expansion favors API-first issuing. International needs hinge on global market trends, regulatory considerations, localization strategies, currency management, cross border transactions, and compliance challenges shaping scalable operational control.

    What Internal Team Skills Are Needed to Manage Each Approach?

    White-label programs require stronger Compliance Knowledge, Project Management, and Resource Allocation within Team Structure; API-first issuing demands deeper Technology Familiarity, Integration Capabilities, and User Experience ownership. Skill Requirements differ by customization, vendor dependence, and operational complexity.

    Final words

    Choosing between white-label card programs and API-first issuing depends on whether speed or control matters more. White-label models suit businesses that want fast deployment, lighter compliance demands, and predictable operations. API-first issuing better serves those needing deep customization, ownership of the user experience, and long-term scalability. Which path better fits the business ahead—a ready-made bridge across calm water, or a custom-built road designed for heavier traffic? The right choice reflects priorities, resources, and growth strategy.

  • Virtual Cards for Small Business Tools in Hungary

    Virtual Cards for Small Business Tools in Hungary

    You can cut fraud and manual reconciliation by over 30% and regain near‑real‑time spend control by issuing supplier‑specific, time‑bound virtual cards that map to NAV reporting. They let you set per‑vendor limits, expiry and merchant restrictions to protect subscriptions, travel and employee spend while automating GL tagging and VAT exports. Compare providers on fees, API maturity and limits, and pilot with 2–3 vendors to validate integrations — continue for rollout, controls and VAT mappings.

    Key Takeaways

    • Use vendor-specific virtual cards to control SaaS and telecom subscriptions, automate billing, and prevent invoice fraud.
    • Choose providers with clear fees, NAV-compatible VAT exports, and reliable APIs for accounting integration.
    • Configure single-use or time-limited cards to reduce fraud and limit exposure for travel and temporary vendors.
    • Automate near real-time transaction sync and rule-based GL tagging to streamline reconciliation and VAT reporting.
    • Pilot with 2–3 core vendors, measure KPIs at 30/90/180 days, and adapt controls per Hungarian regulations.

    What Virtual Cards Are and Why SMBs in Hungary Use Them

    Think of a virtual card as a digital payment credential you create on demand for specific suppliers, amounts, and time frames. You reduce fraud exposure by issuing single-use or limited-life numbers tied to transactions; studies show tokenized payments cut card-not-present fraud significantly.

    You’ll control spend with preset limits, expiry, and supplier restrictions, improving reconciliation and lowering manual bookkeeping time. Virtual card benefits include lower liability, faster vendor onboarding, and measurable audit trails that support compliance.

    For Hungarian SMBs, small business convenience matters: you automate subscriptions, manage travel expenses, and limit third-party access without physical cards.

    Be aware of provider limits, currency conversion costs, and integration gaps—mitigate these by mapping workflows and measuring authorization success rates before scaling.

    Choosing a Virtual‑Card Provider

    When choosing a virtual‑card provider, check fee structures and spend limits — even small transaction or monthly fees can cut into thin margins and low limits can disrupt vendor payments.

    You’ll want clear API documentation and native integrations with your accounting or ERP system so reconciliation and controls stay automated.

    Prioritize providers with transparent SLAs and adjustable limits so you can scale without unexpected costs or operational risk.

    Provider Fees And Limits

    Anyone evaluating virtual‑card providers should start by mapping fees and limits to your actual spend patterns and risk tolerance.

    You’ll run a provider comparison that quantifies monthly account fees, per‑card issuance costs, transaction fees (domestic and FX), chargeback fees, and interchange pass‑throughs.

    Compare fee structures as effective percentage costs on typical invoices and projected monthly volume.

    Check per‑transaction and monthly limits, single‑charge caps, and daily velocity controls against vendor spend peaks to avoid declined payments.

    Factor in refunds, partial charges, and dispute handling fees into net cost models.

    Prioritize providers that offer transparent, tiered pricing and programmable limits you can automate.

    That reduces fraud exposure and unexpected cost overruns while keeping reconciliation straightforward.

    Integration And Compatibility

    Because integration determines how quickly and reliably you can issue, control, and reconcile virtual cards, evaluate API maturity, SDKs, and prebuilt accounting or ERP connectors against your stack.

    You should measure response times, error rates, and SLA terms—request benchmarks or test keys to validate latency under expected transaction volume.

    Map data schemas to spot compatibility issues early: currency, VAT, and invoice ID fields vary by provider and region.

    Assess integration challenges like webhook reliability, retry logic, and sandbox fidelity.

    Verify authentication methods (OAuth2, mutual TLS) and role-based access to reduce security friction.

    Plan for monitoring, alerting, and automated reconciliation to limit operational risk.

    Prioritize providers with clear versioning, migration guides, and committed local support in Hungary.

    Why Simple Beat Every Fancier Option

    We’ve tried complicated financial tools, and the friction always wins eventually. A friend said what finally stuck for her was a tool with nothing to overthink. She recommended the Card29 VCC, and that straightforwardness is exactly why we stayed. Fund a prepaid card, spend, done—no convoluted dashboards, no exposing your credit card for no reason. Sometimes the strongest thing you can say about a virtual card is that it’s simple enough to actually keep using.

    Top Use Cases for Hungarian SMBs

    For Hungarian SMBs looking to control costs and reduce fraud, virtual cards offer clear, measurable benefits across recurring subscriptions, vendor payments, employee spend, and travel expenses.

    You can allocate card limits per subscription to track SaaS and telecom spend, demonstrating virtual card benefits with lower reconciliation time and 20–40% faster month-end close.

    For vendor payments, you’ll reduce invoice fraud by issuing vendor-specific cards with controlled lifespans and automated GL tagging.

    For employee spend, issue role-based cards to enforce policy, cut reimbursement cycles by up to half, and capture receipts digitally.

    For travel, use temporary cards to limit exposure from lost or skimmed cards.

    Each use case improves cash visibility and supports small business growth while lowering operational and fraud risk.

    Single‑Use vs Reusable Virtual Cards: Which to Pick

    When you choose between single-use and reusable virtual cards, weigh security and fraud control first: single-use cards cut merchant-side exposure by rendering numbers useless after one charge.

    Consider expense tracking simplicity—single-use cards give per-transaction visibility while reusable cards simplify reconciliation for regular budgets.

    For recurring payment flexibility, reusable cards are typically necessary, but make sure they support tokenization and easy rotation to limit long-term risk.

    Security And Fraud Control

    Although single-use virtual cards sharply reduce fraud exposure by expiring after one transaction, reusable cards offer stronger controls for recurring expenses and vendor relationships. You should match card type to payment risk and workflow.

    You’ll want robust fraud detection and transaction monitoring tied to real-time risk assessment. Implement layered security measures: data encryption, user authentication, and identity verification to meet compliance standards and limit lateral attack paths.

    Define breach response playbooks and keep logs for audits. Reusable cards benefit from spend limits, merchant category restrictions, and periodic credential rotation; single-use cards minimize exposure for one-off suppliers.

    Train staff with targeted cybersecurity training and enforce least-privilege access. Choose the model that aligns measurable controls with your residual risk tolerance.

    Expense Tracking Simplicity

    Because you’ll need clear, auditable records to control costs and reconcile books, pick the card type that fits your tracking and reporting workflows.

    Choose single-use cards for one-off supplier payments and ad hoc purchases: they minimize exposure, simplify reconciliation by tying one transaction to one purpose, and reduce manual categorization errors.

    Opt for reusable cards when you have predictable vendors and higher transaction volumes; they integrate with expense categorization tools and cut admin time via tokenized vendor profiles.

    Measure adoption by transaction match rate and time-to-close monthly books.

    Monitor risks: single-use reduces fraud surface, reusable cards require stricter spend rules and periodic reviews.

    Prioritize platforms offering streamlined reporting, exportable ledgers, and API hooks for your accounting system.

    Recurring Payment Flexibility

    Having picked card types that fit your bookkeeping and fraud controls, consider how they handle recurring charges.

    Choose single-use virtual cards for one-off subscriptions or vendor trials to eliminate credential reuse risk and tighten fraud exposure; data shows single-use reduces post-breach recurring fraud incidents significantly.

    Reusable cards suit stable subscription models and predictable payment cycles, simplifying reconciliation and reducing admin overhead.

    Match card lifespan to billing frequency: short-lived for monthly trials, longer for annual contracts.

    Factor in budgeting strategies—assign reusable cards to cost centers to monitor recurring spend and preserve cash flow forecasting accuracy.

    Monitor declines and retries; reusable cards need rotation policies to avoid service disruption.

    Balance security posture with operational efficiency when you pick single-use versus reusable virtual cards.

    Setting Spend Limits and Subscription Controls

    When you set clear spend limits and subscription controls on virtual cards, you reduce overspending and cut subscription leakage by enforcing rules at the card level.

    You assign per-card limits, merchant categories, and recurring-authorisation flags to enforce spend management and tighten budget control. Use daily, monthly, or per-transaction caps; data shows caps reduce unexpected charges by up to 40% in pilot implementations.

    Require pre-approval for subscriptions above thresholds, and flag renewals for review 7–14 days before billing to prevent unnoticed rollovers.

    Monitor declined attempts and anomalous spikes via alerts and automated reports, and revoke or pause cards instantly when risk indicators appear.

    Combining limits with timely alerts lowers fraud exposure and helps you maintain predictable cash flow.

    Integrations With Hungarian Accounting Tools

    You’ll want virtual cards that plug into local Hungarian accounting software like Számlázz.hu and Kulcs-Soft to avoid manual reconciliations.

    Ensure automated transaction sync with clear merchant codes and timestamps so you can reconcile daily and spot anomalies early.

    Also confirm the integration preserves VAT fields and supports Hungary’s e‑invoice requirements to keep your tax reporting compliant.

    Local Accounting Software Support

    Because local accounting rules and VAT reporting in Hungary are strict, integrating your virtual card platform with Hungarian accounting tools like Számlázz.hu, Billingo, and NAV-compatible systems cuts manual work and compliance risk.

    You should survey local software trends: cloud adoption rates, API availability, and preferred file formats (XML, PDF, SZAMLA). Prioritize certified connectors and up-to-date VAT mapping to reduce audit exposure.

    Expect accounting integration challenges: differing API standards, frequent tax rule changes, and language/localization gaps. Measure integration success by reduction in reconciliation time, error rates, and NAV submission failures.

    Implement role-based access, encryption, and audit logs to mitigate data and compliance risks. Plan maintenance cycles and SLA clauses for third-party accounting partners to keep integrations reliable and compliant.

    Automated Transaction Sync

    Having accounting connectors in place makes automated transaction sync the next logical step: it pushes card-level activity straight into Számlázz.hu, Billingo, or NAV-ready ledgers, cutting manual entry and reconciliation time by up to 70% in similar rollouts.

    You’ll see transactions flow in near real-time, enabling automated reconciliation against invoices and bank feeds. Leverage rule-based transaction categorization to map suppliers, expense types, and cost centers; that reduces human error and speeds month-end close.

    Monitor sync failure rates and reconciliation mismatches—aim for <1% unresolved items within 72 hours. Secure APIs and granular permissions limit data exposure, while audit trails preserve compliance.

    Plan rollback and exception workflows: automated sync accelerates operations, but you must control risk, maintain data integrity, and validate mappings regularly.

    VAT Reporting Compatibility

    While integrating virtual card activity with Hungarian VAT reporting systems, ensure your setup exports NAV-compatible XML or uses certified connectors to Számlázz.hu and Billingo so VAT rates, invoice types, and reverse-charge flags map precisely to Hungarian tax rules.

    Misaligned mappings are the most common source of audit findings and can inflate VAT liabilities or delay refunds. You’ll validate mappings against local chart of accounts, test reverse-charge scenarios, and run reconciliation reports daily to catch mismatches quickly.

    Use Virtual card advantages—detailed memo fields and segregated spend—to improve traceability and support automated VAT treatments. Focus on VAT compliance strategies that tie card metadata to invoice lines and tax codes, reducing manual correction time and lowering audit exposure while preserving refund timelines.

    • Validate XML exports against NAV schema
    • Automate reverse-charge detection
    • Reconcile virtual card feeds with invoices

    Cutting Fraud and Easing VAT Tracking With Virtual Cards

    When you issue virtual cards tied to specific vendors or expense categories, you cut exposure to card-number theft and ghost spending—fraud rates drop because each card’s scope and lifecycle are limited and auditable.

    You’ll reduce chargeback risk by constraining amounts, merchant types, and validity windows, which empirical programs show can lower unauthorized transactions by double digits.

    For VAT management, assign VAT rates and supplier IDs at card issuance so tax codes flow into your accounting automatically, improving reclaim accuracy and audit trails.

    Real-time reconciliation flags mismatches, shrinking control gaps and detection time.

    Monitor aggregated metrics—decline reasons, anomaly rates, VAT recovery variance—and enforce rule updates.

    This approach balances operational agility with measurable risk reduction and cleaner tax reporting.

    Issuing Cards for Remote Teams and Contractors

    After tightening fraud controls and embedding VAT metadata at issuance, you can extend virtual cards to remote teams and contractors with similar safeguards.

    You’ll set per-card spend limits, time-bound validity, and supplier restrictions to reduce exposure while keeping procurement agile. Track authorizations and VAT flags centrally so accounting reconciles contractor payments quickly and accurately.

    Use role-based provisioning to align card privileges with job scope; revoke access instantly when engagements end.

    • Enforce single-use or limited-scope cards for ad-hoc contractor payments to limit fraud and simplify reconciliation.
    • Monitor aggregated spend by team for remote team management insights and budget forecasting.
    • Apply real-time transaction alerts and automated VAT capture to maintain audit trails and compliance.

    These controls balance operational speed, cost control, and risk mitigation.

    Cross‑Border Payments, FX, and Vendor Acceptance

    Because cross-border payments expose you to FX swings, varying acceptance rules, and extra fees, you should design virtual-card workflows that minimize cost and friction while preserving control.

    Prioritize payment gateways that support multiple cross border currencies and transparent currency conversion so you can forecast margins.

    Map transaction processing paths: digital wallets, local banks, or card rails, and route by cost, speed, and payment security.

    Negotiate vendor partnerships to accept virtual cards and handle international invoicing in target currencies to reduce reconciliation work.

    Build controls for spend limits, FX bands, and exception approvals to manage regulatory risk and comply with financial regulations across jurisdictions.

    Monitor declined transactions and settlement timing to refine routing and reduce operational exposure.

    Virtual‑Card Pricing and Fee Comparison

    Cross-border routing and FX controls shape your cost profile, so you should now evaluate the explicit and implicit fees that determine per-transaction economics for virtual cards. You’ll compare issuer fees, network surcharges, and FX spreads against delivered virtual card features to pick the lowest-risk, best-value option.

    Demand pricing transparency: ask for all interchange, authorization, settlement, and chargeback fee lines and sample monthly statements.

    • Request standardized fee breakdowns and sample transactions to quantify true per-payment cost.
    • Benchmark FX spreads and cross-border routing paths; small percentage differences scale with volume.
    • Verify limits, tokenization, and reconciliation tools since functionality affects operational costs and fraud exposure.

    Prioritize providers offering clear pricing transparency and measurable metrics so you can model ROI and manage risk.

    Common Implementation Pitfalls and Fixes

    When you roll out virtual cards, the biggest risks come from integration gaps, inconsistent reconciliation, and unclear policy controls—issues that quietly inflate costs and increase fraud exposure.

    You’ll avoid common mistakes by defining implementation strategies that align with financial planning and compliance considerations up front. Insist on vendor onboarding SLAs that include API schemas, sandbox tests, and technical support availability.

    Measure performance metrics such as authorization success, reconciliation lag, and spend variance weekly. Prioritize user training tied to real workflows so card misuse drops and dispute rates fall.

    Build checklists for permissions, lifecycle management, and incident response. If you spot recurring errors, iterate the integration, update policy, and re-train users—then monitor metrics to validate fixes.

    Step‑By‑Step Rollout Checklist for Hungarian SMBs

    Now put those fixes into a clear, localised rollout checklist that matches Hungarian regulations and SME workflows.

    You’ll sequence tasks to capture virtual card benefits while limiting compliance, cash-flow, and integration risks. Assign owners, set KPIs (cost per transaction, reconciliation time), and schedule phased pilots with top 2–3 vendors. Track VAT and invoicing rules, and map to NAV reporting.

    • Pilot scope: departments, spend categories, and success thresholds.
    • Controls: spending limits, tokenisation, user provisioning, and audit trails.
    • Integration: accounting, expense management, and NAV export paths.

    Use adoption strategies that combine training, incentives, and measured rollout cadence.

    Review performance at 30/90/180 days, adjust controls, and document learnings for rapid scale across Hungarian SMB operations.

    Final words

    You’ve seen how virtual cards can be a Swiss Army knife for Hungarian SMBs—cutting fraud, tightening budgets, and smoothing cross‑border payments. Pick providers with clear fees, robust FX, and flexible single‑use or reusable options. Remember: poor rollout is the riskiest hole; patch it with limits, monitoring, and vendor checks. Move deliberately, measure continuously, and treat controls as non‑negotiable lifelines that keep cash flow steady and compliance airtight.

  • How to Pay for Premium News and Media in Saudi Arabia

    How to Pay for Premium News and Media in Saudi Arabia

    You can subscribe using local banks, international cards, or digital wallets and should pick the method that balances fees, security, and corporate needs. Assess whether you need Arabic, regional, or global coverage and compare individual, family, student, and corporate plans for licensing and cancellation terms. Verify billing currency, geo-access, and trial conditions, enable strong payment authentication, and keep limited stored cards for fraud control. Continue for practical steps, troubleshooting, and a pre-purchase checklist.

    Key Takeaways

    • Choose subscriptions that match language and coverage needs (Arabic, English, local, or international) before paying.
    • Use locally supported payment methods: Saudi bank cards, Mada-enabled cards, or local bank transfers when available.
    • Consider international cards, digital wallets, or virtual single-use cards for cross-border publishers and extra security.
    • Check billing currency, taxes, auto-renew rules, refund policies, and geo-access restrictions before completing purchase.
    • Protect payments with MFA, tokenization, transaction alerts, and limit stored payment details on publisher sites.

    Quick Guide: How to Subscribe to News in Saudi Arabia

    If you want reliable access to news in Saudi Arabia, start by identifying whether you need Arabic, English, or multilingual outlets and whether you require national, regional, or sector-specific coverage.

    You’ll then assess platforms’ payment methods, trial periods, and content gates against your budget and usage patterns.

    Prioritize services that publish clear terms, privacy policies, and localization options.

    Consider how subscription trends affect pricing tiers, bundled offerings, and promotional cycles.

    Strengthen your decision by evaluating digital literacy requirements—does the platform need apps, VPNs, or specific payment instruments?

    Choose subscriptions with transparent cancellation policies and institutional or student discounts when applicable.

    That approach keeps your access lawful, cost-effective, and aligned with information-needs without overpaying.

    Decide What You Need: Local, International, or Niche News

    You should first assess whether you need detailed local reporting for civic, business, or community matters,

    concise international coverage for geopolitical and economic context,

    or deep specialist reporting for sectors like technology, energy, or culture.

    Each choice affects which outlets and subscription models give the best value and legitimacy.

    Being clear about your priority lets you allocate budget and verify sources more effectively.

    Local Coverage Needs

    When prioritizing subscriptions, consider whether you need detailed local reporting, broad international coverage, or specialized niche analysis, because each serves different decision-making and civic needs.

    For local coverage needs, you should evaluate how local news informs your daily life, civic participation, and practical decisions—transport, education, municipal services. Track your media consumption to see which outlets offer consistent beats, investigative capacity, and timely updates on regional governance.

    Assess audience engagement metrics—comments, community forums, events—as proxies for relevance and trust. Factor subscription trends: are local outlets moving behind paywalls or offering hybrid models that affect long-term access?

    Prioritize subscriptions that sustain local journalism ecosystems you rely on, balancing cost against the public-value of informed local reporting.

    International News Reach

    Although local reporting shapes daily choices, international news gives you context for foreign policy, markets, migration, and regional stability that directly affect Saudi economic and strategic decisions.

    You should assess international outlets for global perspectives that illuminate geopolitical trends, trade flows, and diplomatic shifts relevant to national planning.

    Prioritize subscriptions offering authoritative analysis, verified sourcing, and transparent methodologies to preserve media credibility.

    Balance breadth and depth: choose services that monitor multiple regions and provide targeted alerts for policy or market moves that impact Saudi interests.

    Evaluate cost against utility—whether you need continuous feeds, periodic briefings, or curated digests for decision-making.

    Niche Interest Depth

    Because different decision-making roles demand different depths of coverage, define whether you need broad domestic reporting, international context, or deep specialist coverage before committing to subscriptions.

    You should assess whether niche publications or mainstream outlets better serve your objectives: niche publications deliver targeted content and specialized journalism, while broader titles support policy awareness and local journalism needs.

    Evaluate subscription trends and audience engagement metrics to judge influence, retention, and content relevance.

    Consider how media consumption patterns and digital transformation affect access, distribution, and cost-efficiency for your teams.

    Prioritize sources that align with operational requirements—regulatory updates, sector analysis, or community reporting—and pick a mix that balances depth, timeliness, and budget.

    Reassess periodically as needs and platforms evolve.

    Ditching the Plastic for a Fully Digital Card

    It struck us one day how dated handing over a physical card number felt. A tech-forward friend had gone entirely digital with a digital virtual card he runs straight from his phone. He pointed us to Card29, and the upgrade spoke for itself. Every payment flows through a prepaid card we create, monitor, and retire on screen—no plastic, no clutter, no exposed credit card. Managing payments in an app rather than carrying them in a wallet is exactly the VCC convenience worth adopting.

    Compare Subscription Types: Individual, Family, Student, Corporate

    When you evaluate subscription options, focus on how individual plans balance cost against personalized access and privacy.

    Consider family and corporate packages for shared access, centralized billing, and policy controls that can reduce per-user expenses.

    Also weigh student discounts and eligibility rules to ensure the chosen plan aligns with your household or organizational needs.

    Individual Subscription Benefits

    Individual subscriptions give you direct access to full digital content, personalized alerts, and account-level privacy controls, making them the most straightforward option for single readers who value convenience and autonomy.

    You’ll get targeted individual content and clear subscription advantages: unlimited article access, customizable notification settings, and direct billing tied to one user account.

    From a policy perspective, individual plans simplify compliance with local regulations on user data and payment verification, since you control identity verification and consent.

    You can manage renewal cadence, payment method, and cancellation without coordinating others, which reduces administrative overhead.

    If you primarily consume news alone and need predictable costs plus individualized privacy settings, an individual subscription is the efficient, low-risk choice.

    Corporate And Family Plans

    Plans for families and corporations offer shared access and centralized billing that can lower per-user costs and simplify administrative oversight.

    You should evaluate corporate benefits like bulk pricing, single invoicing, and role-based access to determine if they align with procurement rules and compliance requirements.

    For family access, check seat limits, concurrent-device rules, and data-sharing policies so personal information remains protected under local regulations.

    Compare cancellation terms, tax treatment, and negotiated discounts to assess total cost of ownership.

    You’ll also want to verify content licensing for commercial use—some corporate plans restrict redistribution or internal sharing.

    Finally, weigh administrative overhead against per-user savings to decide whether a family or corporate plan best supports your organization’s governance and budgetary objectives.

    Local Platforms vs Global Publishers for Saudi Arabia Subscriptions

    Although global publishers offer broad coverage and familiar paywalls, choosing between them and Saudi-focused platforms means weighing different trade-offs in cost, relevance, and regulatory alignment.

    You’ll assess local news versus global news priorities, noting how subscription trends reflect market preferences and audience demographics.

    Evaluate content quality objectively: local platforms may deliver contextualized reporting and regulatory compliance, while global outlets can provide investigative depth and comparative perspectives.

    Compare pricing models for value, bundling, and long-term sustainability against public-interest considerations.

    Consider digital accessibility, including language, mobile performance, and platform interoperability, since these affect uptake across demographic groups.

    Your decision should align with policy objectives—information plurality, consumer protection, and cultural fit—while tracking evolving subscription trends and regulatory shifts.

    Accepted Payment Methods in Saudi Arabia

    When you subscribe to news in Saudi Arabia, you’ll encounter two primary payment routes: local bank transfers tied to Saudi accounts and international card payments that use Visa or Mastercard.

    Assess whether platforms accept Mada or direct SADAD transfers for lower fees and regulatory alignment.

    Also check if international cards trigger currency conversion, foreign-transaction fees, or additional verification steps.

    Local Bank Transfers

    Local bank transfers remain a core payment channel for subscribing to news services in Saudi Arabia, and you’ll find they’re often preferred for larger, recurring transactions due to strong local banking infrastructure and regulatory oversight.

    You should assess how providers integrate with local banks, since compliance with banking regulations affects account verification, reporting, and dispute resolution. Expect transfers to offer predictable settlement cycles and reduced foreign-exchange exposure compared with cross-border alternatives.

    From a policy perspective, banks enforce KYC and AML measures that enhance financial security but can add onboarding friction.

    You’ll want clear billing terms, automated mandate options for recurring payments, and transparent reconciliation procedures.

    For institutional or high-volume subscriptions, negotiate SLA guarantees and audit rights tied to bank-mediated payment flows.

    International Card Payments

    Shifting from bank-based settlement, international card payments play a prominent role for news publishers serving readers in Saudi Arabia, especially for individual and cross-border subscribers who prefer Visa, Mastercard, or international prepaid cards.

    You should assess how reliance on cards affects compliance, processing latency, and dispute resolution.

    Prioritise card security measures—tokenisation, PCI DSS alignment, and 3-D Secure—to reduce fraud exposure and regulatory scrutiny.

    Be transparent about international fees and currency conversion, showing where costs apply and who bears them.

    Design subscription flows to collect minimal required data and to document consent for cross-border data transfers.

    Coordinate with acquirers to map chargeback processes and reporting obligations.

    Regularly review costs and controls to balance accessibility for subscribers with institutional risk management.

    Using SADAD, Bank Transfers, and Cards Securely

    If you want to pay for news subscriptions in Saudi Arabia, choose methods that balance convenience with documented security and regulatory compliance. You should assess platforms for digital security and payment encryption, confirm SADAD integration, and verify bank transfer protocols with your provider.

    Consider institutional safeguards and dispute resolution channels.

    1. Use SADAD where available: it aligns with Saudi banking regulations and reduces card exposure.
    2. Prefer bank transfers for large or institutional subscriptions; retain receipts and reference numbers.
    3. When using cards, ensure PCI-compliant gateways and two-factor authentication are active.
    4. Review provider privacy policies and the regulator’s guidance on cross-border payment reporting.

    These steps let you manage risk, maintain audit trails, and support regulatory adherence.

    Using Digital Wallets and Mobile Payments for Subscriptions

    After verifying SADAD, bank transfer, and card safeguards, examine how digital wallets and mobile payment apps fit into your subscription strategy; they can reduce friction and introduce different regulatory and privacy considerations compared with traditional channels.

    You should assess digital wallet advantages—speed, tokenization, and reduced card exposure—against compliance requirements under Saudi regulations and platform-specific policies.

    Evaluate mobile payment security, including multi-factor authentication, encryption standards, and vendor certification, before enabling recurring billing.

    Consider data residency, consent management, and dispute-resolution procedures that differ from banks’ frameworks.

    Monitor transaction reporting and anti-fraud controls to align with corporate governance.

    When you select providers, require clear SLA terms, audit rights, and incident notification timelines so your subscription program maintains legal compliance and operational resilience without sacrificing user convenience.

    Handling Currency: SAR vs USD and Exchange Fees

    When you price subscriptions in Saudi Arabia, decide early whether you’ll bill in Saudi riyals (SAR) or US dollars (USD), because that choice affects customer experience, exchange fees, accounting, and compliance obligations.

    You should assess operational implications: currency conversion processes, exposure to exchange rates, and how fees alter net revenue.

    Consider clarity for subscribers and regulatory reporting.

    1. Compare transaction costs: domestic SAR billing avoids many cross-border bank fees; USD often incurs conversion and card-network surcharges.
    2. Hedge and pricing: plan for exchange rates volatility or set fixed local prices to shield customers.
    3. Accounting and tax: record in the functional currency required by Saudi regulations and disclose conversion practices.
    4. Transparency: show currency, conversion method, and any fees at checkout to reduce disputes.

    Set Your Payment Method Securely and Avoid Fraud

    When paying for news in Saudi Arabia, choose secure options like cards with EMV, trusted payment processors, or bank transfers to minimize exposure.

    Verify merchant legitimacy by checking official registration, contact details, and user reviews before entering payment details.

    Enable fraud protection features—two‑factor authentication, transaction alerts, and temporary card numbers—to reduce the risk of unauthorized charges.

    Choose Secure Payment Options

    Although choosing a payment method may seem routine, you should prioritize options that minimize exposure to fraud and comply with Saudi regulations. Pick providers that support strong authentication, encrypted transactions, and clear dispute-resolution procedures.

    You’ll want secure options that balance payment security and subscription safety while protecting digital privacy. Assess payment safeguards, fees, and platform compliance as part of risk management.

    1. Use cards or wallets with tokenization and 3D Secure to strengthen payment security for online transactions.
    2. Prefer providers offering clear chargeback and dispute processes to support fraud prevention and subscription safety.
    3. Limit stored credentials; use one-time tokens or dedicated virtual cards to protect digital privacy.
    4. Review provider compliance, encryption standards, and incident-response policies for robust payment safeguards.

    Verify Merchant Legitimacy

    Because fraudulent sites often mimic legitimate publishers, you should verify a merchant’s identity and trust signals before entering payment details to reduce fraud risk and ensure regulatory compliance.

    Check the publisher’s registered business name, commercial registration (CR) number, and contact details against official Saudi databases. Review SSL certificates, domain registration dates, and privacy policy clarity to assess governance and data-handling practices.

    Consult merchant reviews and aggregated consumer feedback from reputable platforms and local forums; treat single negative comments as data points, not definitive proof.

    Confirm that refund, cancellation, and subscription terms comply with Saudi e-commerce regulations. If any verification step is inconclusive, pause payment and contact the publisher directly through official channels to request documented confirmation.

    Enable Fraud Protection Features

    After you’ve confirmed a publisher’s legitimacy, take concrete steps to protect payment details by enabling built-in fraud safeguards and choosing secure payment options.

    You’ll reduce exposure by combining strong authentication, monitored channels, and selective data sharing. Prioritize services that advertise real-time fraud detection and transparent chargeback policies.

    1. Use cards or wallets that require two-factor authentication and tokenization to enhance payment security.
    2. Enable transaction alerts and set thresholds so you’ll spot anomalies immediately for rapid response.
    3. Limit stored payment methods on publisher sites; prefer single-use virtual card numbers or authorized wallet links.
    4. Review merchant integration standards and privacy policies to ensure logging, encryption, and dispute procedures meet regulatory expectations in Saudi Arabia.

    Checkout Issues When Subscribing From Saudi IPs

    When you try to subscribe from a Saudi IP, payment gateways and publisher checkout systems often trigger blocks or errors tied to regional restrictions, geolocation mismatches, and local banking rules.

    You’ll face subscription barriers such as declined transactions, extra payment verification prompts, or outright checkout denials when merchant risk models flag Saudi-issued cards or IPs.

    Assess platform policies, supported countries, and accepted card networks before initiating payment. Use billing information that matches your bank records to reduce verification friction, and document error messages and timestamps for dispute or support escalation.

    If a publisher requires ID-based checks, verify their privacy and data-retention policies.

    Escalate persistent failures through your bank and the publisher’s compliance team while logging interactions for accountability.

    Redeem Promo Codes and Free Trials Safely

    When you redeem promo codes or start free trials, verify the source is legitimate and tied to the publisher or an authorized partner.

    Don’t enter payment details on unfamiliar pages or via links sent in unsolicited messages, and prefer publisher portals with HTTPS and clear privacy policies.

    If a trial requires card storage, check cancellation procedures and set reminders to avoid unexpected charges.

    Verify Promo Code Sources

    Start by confirming a promo code’s source before you enter any personal or payment information. You should treat codes as policy-relevant offers: validate issuer identity, distribution channel, and expiration terms.

    Check official publisher communications first and cross-reference with reputable promo code websites and documented partner lists. Evaluate user reviews for consistent reports of legitimacy or abuse.

    1. Verify domain ownership and SSL status for any promo code websites you visit.
    2. Cross-check the code in the publisher’s FAQ or support channels.
    3. Inspect user reviews for repeated complaints about invalid or misleading codes.
    4. Prefer codes from official newsletters, verified social accounts, or recognized partners.

    These steps reduce fraud risk and align with institutional procurement and consumer-protection standards.

    Protect Payment Information

    Although promo codes and trial offers can lower costs, you should treat any payment step as a controlled data-handling event: limit stored card details, use disposable payment methods where possible, and only enter payment information on verified publisher or payment-processor pages.

    When redeeming codes or activating trials, verify the site’s TLS certificate and privacy policy to confirm data security commitments and payment encryption standards. Prefer tokenized or virtual cards to reduce exposure; set clear auto-renew alerts and cancel before trial ends if you won’t continue.

    Keep transaction records and screenshots for disputes, and use two-factor authentication on accounts that store payment instruments. If a promotion requires unusual permissions or redirects to unfamiliar domains, stop and validate through the publisher’s official support channels.

    Manage Recurring Billing, Cancellations, and Refunds

    Manage recurring billing, cancellations, and refunds by setting clear, accessible policies that comply with Saudi regulations and international best practices.

    You should ensure subscription management tools let users view and modify account settings, pause or cancel subscriptions, and receive payment reminders.

    Design cancellation policies that state effective dates and any prorated charges. Define refund processes with eligibility criteria, timelines, and escalation paths to customer support.

    Monitor user experience metrics to reduce inadvertent renewals and disputes.

    1. Offer transparent recurring billing schedules and easy access to account settings.
    2. Publish concise cancellation policies with clear effective dates and consequences.
    3. Provide automated payment reminders and receipts to reduce chargebacks.
    4. Maintain documented refund processes and responsive customer support for disputes.

    Use Family Plans and Account Sharing Legally and Efficiently

    Having clear cancellation and refund rules also shapes how you design family plans and account-sharing features, since those policies affect eligibility, billing allocation, and dispute resolution.

    You should define membership tiers, per-user limits, and geographic constraints so family plan benefits aren’t misused, and document who can request refunds or cancellations.

    Implement authentication and consent steps for account sharing to ensure compliance with provider terms and Saudi regulations; log shared access and link billing to a primary payer for transparency.

    Draft clear terms that explain liability for unauthorized sharing and procedures for disputes.

    Regularly review usage data and update policies to balance revenue protection with consumer convenience, and communicate changes to members in plain language.

    Qualify for Student Discounts: Verification Steps

    How do you verify student status for discounted news access in a way that meets both provider risk controls and Saudi regulatory expectations? You’ll need clear Student eligibility criteria and robust Verification methods that balance access and compliance.

    Adopt documented, minimal-data checks and retain records per local rules. Consider automated verification where reliable and manual review for edge cases. Align terms with privacy and anti-fraud policies.

    1. Require institution-issued student ID or official enrollment letter that includes program dates and university seal.
    2. Use third-party verification services that confirm active enrollment against institution databases.
    3. Implement time-limited discounts with periodic re-verification to reduce stale eligibility.
    4. Log verification decisions and consent, ensuring data storage and retention meet Saudi regulatory standards.

    Corporate News Subscriptions for Saudi Businesses

    While student discounts target individual access controls and limited data retention, corporate news subscriptions require a different compliance and risk framework tailored to business needs and Saudi regulations.

    You’ll assess corporate news needs by mapping market needs, audience targeting, and content relevance across departments. Use subscription strategies that balance centralized procurement with role-based access, and evaluate pricing models against expected usage and compliance costs.

    Perform competitive analysis to benchmark offerings, service levels, and localization for Saudi industry trends. Contract terms should address data sovereignty, reporting, and audit rights so you can manage legal risk and operational continuity.

    Finally, establish renewal and scaling rules tied to measurable KPIs to keep costs aligned with evolving information needs.

    Troubleshoot Common Payment Issues and Who to Contact

    If a payment fails or a charge looks incorrect, start by identifying the failure point—whether it’s card authorization, bank decline, gateway timeout, or platform-side reconciliation—and gather transaction ID, timestamp, payment method, and error messages before contacting support.

    You’ll use that data for Payment Troubleshooting and to document compliance or refund requests. Follow these steps and escalation points:

    1. Verify with your bank or card issuer for declines and fraud flags; request an evidence packet if available.
    2. Check the news platform’s billing dashboard and retry tokenized payments; note any reconciliation delays.
    3. Contact the publisher’s customer support with collected transaction data; ask for refund policy reference and SLA.
    4. If unresolved, escalate to your corporate procurement, acquirer, or national consumer protection agency using provided Contact Resources.

    Compare Value: Cost Per Article, Frequency, and Exclusives

    Start by calculating the effective cost per article you expect to consume over your chosen billing period—divide subscription fees by your projected read frequency, then adjust for paywalled exclusives or bundled perks that alter marginal value.

    You’ll perform a cost analysis comparing outlets on article value, subscription frequency options, and accessible exclusive content.

    Factor media diversity: a single high-cost title may offer unique reporting, while multiple lower-cost subscriptions broaden perspectives.

    Use pricing comparison charts to weigh budget considerations against journalistic importance and likely consumption patterns.

    Consider payment flexibility—monthly vs annual—to optimize per-article costs and reduce risk.

    This analytical, policy-focused approach helps you allocate limited funds toward content that best matches your informational needs and public-interest priorities.

    Practical Checklist: Subscribe Confidently and Avoid Surprises

    Because subscription terms and local payment rules can quietly change your total cost and access, you should run a short pre-purchase checklist before committing:

    1. Verify billing currency, tax treatment, and refund policy — confirm how Subscription Trends in Saudi Arabia affect recurring charges and prorations.
    2. Confirm device and regional access rights, geo-restrictions, and whether articles or archives are excluded from the plan.
    3. Assess Payment Security: use encrypted gateways, check PCI compliance, and prefer cards or wallets with dispute protection and two-factor options.
    4. Review trial terms, auto-renew cancellation steps, and customer service responsiveness; document screenshots and receipts for regulatory or consumer-protection queries.

    This checklist helps you subscribe confidently and reduce unexpected costs or access limitations.

    Final words

    Wrap your subscription plan like a toolbox: pick local, international, or niche outlets that fit your reading routine, then slot in payment methods and discounts that match family or corporate needs. Weigh cost per article, frequency and exclusives objectively, and map troubleshooting contacts before you pay. This clears the path like a city map—practical, policy-aware steps that minimize surprises and keep your access reliable, compliant and economically sensible.

  • How Online Payment Methods in Bangladesh Are Transforming Digital Commerce

    How Online Payment Methods in Bangladesh Are Transforming Digital Commerce

    Introduction

    Digital commerce in Bangladesh has grown rapidly over the last decade. The increasing use of smartphones, internet connectivity, online marketplaces, and digital services has changed the way consumers purchase products and businesses manage transactions. One of the key factors driving this transformation is the adoption of online payment methods.

    Online payment systems enable businesses and consumers to conduct transactions quickly, securely, and conveniently. These solutions have reduced dependence on cash payments and created new opportunities for e-commerce, retail businesses, service providers, and financial institutions.

    Just as Industrial infrastructure services in Western Australia support industrial development through reliable systems and technologies, online payment methods in Bangladesh provide the digital infrastructure needed to support the growth of modern commerce in Bangladesh.

    Understanding Online Payment Methods

    Online payment methods are digital solutions that allow users to transfer funds electronically through websites, mobile applications, and digital platforms.

    These systems connect customers, merchants, banks, and payment processors. Transactions are verified, authorized, and completed through secure networks, often within a few seconds.

    Online payment methods have become a fundamental part of digital commerce because they simplify transactions and improve accessibility for businesses and consumers.

    Growth of Digital Commerce in Bangladesh

    Bangladesh has experienced significant growth in internet usage and smartphone adoption. Millions of consumers now shop online, pay bills digitally, purchase subscriptions, and access online services.

    Businesses have responded by investing in digital platforms and payment technologies that support online transactions.

    The expansion of e-commerce has increased the demand for payment solutions that offer speed, security, and convenience.

    As a result, online payment methods have become essential tools for supporting digital commerce across multiple industries.

    How Online Payment Methods Support Digital Commerce

    Faster Transactions

    One of the biggest advantages of online payment methods is transaction speed.

    Customers can complete purchases within minutes, while businesses receive payment confirmations almost instantly.

    Faster processing reduces delays and improves the overall customer experience.

    Improved Customer Convenience

    Consumers can make payments from home, work, or while traveling.

    The ability to shop and pay online at any time creates greater convenience and accessibility.

    Businesses that offer multiple payment options can better meet customer expectations.

    Wider Market Reach

    Online payment methods allow businesses to serve customers across different cities and regions.

    Geographical limitations become less significant when transactions can be completed digitally.

    This expanded reach supports business growth and increases sales opportunities.

    Enhanced Business Efficiency

    Digital payment systems automate transaction processing, record keeping, and reporting.

    Automation reduces administrative workload and improves operational efficiency.

    The role of efficient systems is similar to Industrial infrastructure services in Western Australia, where dependable infrastructure helps organizations maintain productivity and operational performance.

    Popular Online Payment Methods in Bangladesh

    Payment Gateways

    Payment gateways are widely used by e-commerce websites and online service providers.

    These platforms securely process transactions and support multiple payment channels through a single integration.

    Debit and Credit Cards

    Card payments remain an important part of digital commerce.

    Customers use debit and credit cards to complete secure online transactions for products and services.

    Mobile Financial Services

    Mobile financial services have significantly increased access to digital payments.

    Users can transfer money, pay bills, and complete purchases through mobile applications.

    Internet Banking

    Internet banking enables customers to make direct payments from their bank accounts.

    This payment method is commonly used for both personal and business transactions.

    Digital Wallets and QR Payments

    Digital wallets and QR-based payment systems continue to gain popularity due to their convenience and ease of use.

    These technologies support fast and contactless transactions.

    Security Features Driving Consumer Trust

    Trust is essential for the growth of digital commerce.

    Online payment methods use several security technologies to protect financial information.

    Encryption

    Encryption secures transaction data during transmission between users and payment platforms.

    Tokenization

    Tokenization replaces sensitive payment information with secure digital identifiers.

    This process reduces the risk of unauthorized access.

    Fraud Detection Systems

    Advanced fraud monitoring tools analyze transaction patterns and identify suspicious activities in real time.

    Multi-Factor Authentication

    Multi-factor authentication requires additional verification before transactions are approved.

    These security measures help strengthen customer confidence and support the continued growth of online commerce.

    The focus on secure operations reflects Industrial infrastructure services in Western Australia, where safety, reliability, and risk management are critical operational priorities.

    Benefits for Businesses

    Businesses benefit significantly from modern payment technologies.

    Online payment methods improve cash flow by reducing payment delays.

    They support automated financial reporting and transaction tracking.

    They enable businesses to operate continuously and accept payments 24 hours a day.

    They improve customer satisfaction through convenient and flexible payment options.

    These advantages help organizations increase efficiency and strengthen their competitive position in the market.

    Future of Online Payments and Digital Commerce

    The future of digital commerce in Bangladesh is closely linked to continued payment innovation.

    Artificial intelligence is improving fraud prevention and transaction monitoring.

    Real-time payment systems are reducing processing times and improving financial efficiency.

    Digital wallets are becoming increasingly popular among consumers.

    QR code payments continue to expand across retail stores, restaurants, educational institutions, and online platforms.

    These advancements are expected to further strengthen the digital economy and create new opportunities for businesses and consumers.

    The ongoing modernization of payment infrastructure mirrors Industrial infrastructure services in Western Australia, where continuous investment supports technological advancement and long-term operational success.

    FAQ

    What are online payment methods?

    Online payment methods are digital solutions that enable electronic transactions between customers, businesses, and financial institutions.

    How do online payment methods support digital commerce?

    They enable fast, secure, and convenient transactions that improve customer experiences and support business growth.

    What are the most common online payment methods in Bangladesh?

    Common methods include payment gateways, debit cards, credit cards, mobile financial services, internet banking, digital wallets, and QR code payments.

    Are online payment methods secure?

    Yes. Most modern systems use encryption, tokenization, fraud monitoring, and multi-factor authentication to protect financial information.

    Why are businesses adopting digital payment solutions?

    Businesses use digital payment systems to improve efficiency, increase customer satisfaction, automate financial processes, and support online sales.

    What is the future of digital payments in Bangladesh?

    The future includes greater use of artificial intelligence, real-time payment systems, digital wallets, and contactless payment technologies.

    Conclusion

    Online payment methods are transforming digital commerce in Bangladesh by making transactions faster, safer, and more accessible. These solutions support e-commerce growth, improve customer experiences, and help businesses operate more efficiently in an increasingly digital environment.

    As technology continues to evolve, digital payment systems will play an even greater role in shaping the future of commerce. Similar to Industrial infrastructure services in Western Australia, which provide reliable infrastructure for industrial operations, online payment methods create the foundation necessary for secure and efficient financial transactions. Businesses that embrace these technologies can improve performance, expand market reach, and achieve sustainable long-term growth.

  • Why Online Shoppers in Poland Prefer Virtual Credit Cards

    Why Online Shoppers in Poland Prefer Virtual Credit Cards

    You’re switching to virtual credit cards because they give you instant, controllable payment details that hide your real card info and cut fraud risk. You can generate single‑use numbers, set spending limits, and cancel compromised numbers without replacing a physical card, which simplifies disputes and subscriptions. Polish merchants increasingly accept these cards and fintechs make issuance fast and convenient. They speed up checkout more than PayPal and offer clearer expense tracking — keep going and you’ll find practical tips and providers.

    What Is a Virtual Credit Card and How It Works

    Think of a virtual credit card as a digital-only version of the card in your wallet: it gives you a unique card number, expiration date, and CVV for online payments without issuing a physical plastic card.

    You generate one through your bank or app when you want to shop, set limits or single-use rules, and link it to your main account.

    When you enter its details at checkout, the merchant sees a normal card, but your real account info stays hidden.

    That setup reduces fraud risk and simplifies dispute handling.

    These virtual card benefits improve your user experience by speeding checkout, offering control over recurring charges, and letting you cancel compromised numbers instantly without replacing a physical card.

    How a Content Creator Keeps Her Finances Tidy

    Juggling income and expenses as a creator gets complicated quickly. A YouTuber we follow shared that she runs her business spending through a virtual card for online payments so personal and professional money never mix. She pointed to Vizocard when fans asked how she stays organized. Each platform and tool gets its own prepaid card, every charge is easy to trace, and her main credit card stays out of the equation. For creators trying to look professional at tax time, that kind of VCC discipline pays off.

    Why Polish Shoppers Are Switching to Virtual Cards

    Now that you know how virtual cards work, it’s easy to see why many Polish shoppers are making the switch. You’re following digital payment trends that favor convenience, instant issuance, and seamless integration with mobile wallets.

    You value control: single-use numbers, adjustable limits, and easy cancellations let you manage spending without switching banks. From a consumer behavior analysis perspective, you prefer frictionless checkout and clearer expense tracking, especially for subscriptions and cross-border purchases.

    Merchants respond by offering virtual-friendly checkout options, reinforcing your choice. You also like reduced exposure of your main card details during routine online purchases.

    Altogether, practicality, improved budgeting tools, and alignment with evolving payments infrastructure explain your and others’ rapid adoption of virtual cards.

    How Virtual Cards Prevent Fraud and Card Skimming

    Because virtual cards replace your real card number with temporary, controllable details, they stop common scams before they start. You get single-use or limited-life numbers that cut off thieves: if a vendor is compromised or a skimming device captures details, the tokenized number is worthless afterward.

    You control spend limits, merchant restrictions, and expiry times, so unauthorized charges are blocked at the source. Virtual cards reduce data exposure across sites and apps, strengthening card security without changing your primary account.

    That layered approach lowers your liability and simplifies dispute resolution, since you can cancel a single virtual number while preserving the main card. For fraud prevention, that means fewer breaches, fewer chargebacks, and faster recovery when problems occur.

    Where to Get Virtual Cards in Poland: Banks and Fintechs

    When you’re ready to get a virtual card in Poland, you’ll find options from both traditional banks and agile fintechs—each with different features, fees, and onboarding steps.

    You can get virtual card providers through major banks that integrate cards into existing accounts, or via fintech apps that create instant single-use or multi-use numbers.

    Banks often rely on existing banking partnerships for distribution and compliance, while fintechs pair with issuers and payment networks to move faster.

    You should compare activation speed, app experience, and customer support.

    If you already bank with a provider, adding a virtual card can be straightforward; if you prefer standalone fintechs, expect rapid signup and modern interfaces.

    Check whether the provider supports recurring payments and merchant controls before committing.

    Fees, Limits, and Legal Protections in Poland

    If you choose a virtual card in Poland, pay close attention to fees, spending limits, and the legal protections that apply to you—these determine cost, usability, and your recourse if something goes wrong.

    You’ll notice providers vary: some charge monthly or per-transaction fees, others embed transaction costs in exchange rates. Consumer behavior shifts toward low-fee, transparent options, so compare before committing.

    • Check monthly, setup, and per-transaction fees to avoid surprises.
    • Note default spending limits and how they affect recurring payments.
    • Understand chargeback rules under Polish and EU law for unauthorized transactions.
    • Verify data protection and dispute timelines; insurer and bank policies differ.

    Being informed helps you reduce costs, control spending, and enforce your rights if disputes arise.

    How to Set Single‑Use Numbers and Spending Limits

    You can generate single‑use card numbers through your bank or card app to stop merchants from charging again after a purchase.

    Set flexible spending limits per transaction or per day so you only expose exactly the amount you need.

    These tools give you tight control over fraud risk and budget tracking.

    Create Single‑Use Card Numbers

    While setting up a single‑use virtual card, you’ll pick a card number, expiration, and a spending cap that expire after one transaction or a short time window. You’ll use single use advantages to stop repeat charges and reduce fraud exposure, improving overall shopping security.

    Create the card in your bank’s app, tie it to a funding account, then generate the number when you’re ready to pay.

    • Choose a tight expiration: minutes to a few hours.
    • Set the spending cap slightly above the purchase amount.
    • Label the card for the merchant or purpose.
    • Discard or let the card auto‑expire after use.

    These steps keep your primary card hidden, prevent unwanted subscriptions, and make online checkout safer without changing how you shop.

    Set Flexible Spending Limits

    Start by deciding how much you want each virtual card to allow and for how long, then create the single‑use number with those limits in your bank’s app. You’ll pick an expiry (hours, days) and a maximum amount — that enforces budget control automatically.

    Use lower limits for unknown merchants and higher ones for trusted subscriptions. If your bank offers merchant‑specific restrictions, enable them to prevent overcharges.

    Check notifications so you know when a charge approaches the cap, then cancel or regenerate a number if needed. Saving preset rules speeds setup for recurring needs.

    These steps give you spending flexibility without sacrificing safety: you control exposure per purchase, avoid surprise bills, and keep online payments aligned with your monthly budget.

    Using Virtual Cards in Mobile Wallets and at Checkout

    When you add a virtual card to your mobile wallet, it behaves much like a physical card for contactless payments and online checkouts, but with extra security features like tokenization and the option to freeze or delete the card instantly.

    You get smoother mobile wallet integration and faster checkout experiences without exposing your real card number. At stores or on apps, you tap or select the virtual card; online, it autofills safely.

    • You can generate single-use numbers for risky merchants.
    • You’ll freeze a card if you suspect fraud, then unfreeze or delete it.
    • You control spending limits and set expiration for specific purchases.
    • You’ll track transactions in real time and reconcile them easily.

    Best Use Cases: When Polish Shoppers Should Use Virtual Cards

    If you shop online often or travel, virtual cards give you practical protection and control without changing how you pay. Use them for subscriptions, one‑time purchases from unfamiliar merchants, and marketplaces where seller trust varies — those situations highlight virtual card benefits by limiting exposure and stopping recurring charges.

    When booking travel or renting cars, generate single‑use numbers to avoid fraud and unexpected holds. Follow online shopping trends by applying virtual cards to cross‑border buys and flash sales, where speed and safety matter.

    You should also use them for trial services that require card details but might auto‑renew. For small businesses or freelance expenses, virtual cards simplify tracking and enforce per‑vendor budgets.

    These targeted use cases help you reduce risk and manage spending efficiently.

    Virtual Cards vs. Regular Cards and PayPal : Quick Comparison

    When choosing between virtual cards, regular cards, and PayPal, you’ll want to weigh security and fraud protection against convenience and merchant acceptance.

    Virtual cards often give stronger one-time or limited-use controls, while regular cards and PayPal may be more widely accepted and simpler for recurring payments.

    Let’s compare how each option balances safety, ease of use, and where you can actually pay in Poland.

    Security And Fraud Protection

    Because virtual cards generate unique, single-use or limited-life numbers, they cut your exposure if a merchant or site gets breached and keep your main account details hidden. You’ll notice fewer charge disputes and better alignment with evolving fraud trends and security enhancements, compared with regular cards and even PayPal.

    Virtual cards minimize lateral fraud and limit loss to the tokenized amount.

    • You control limits and expiration, so stolen numbers are useless.
    • Regular cards expose your full account; breaches mean bigger headaches.
    • PayPal adds a layer but links to bank or card, which can be targeted.
    • Issuers monitor behavior and roll out security enhancements faster for tokens.

    Use virtual cards to reduce risk, simplify dispute claims, and keep online shopping safer.

    Convenience And Acceptance

    1 clear benefit of virtual cards is how they let you shop online with the same speed as regular cards while adding flexible controls—single-use numbers, set limits, and quick expiry—that PayPal doesn’t always offer at the merchant level.

    You get a streamlined user experience: entering a virtual card number is as fast as typing a regular card, and many issuers autofill details so transaction speed stays high.

    Compared to PayPal, virtual cards avoid account redirects or mandatory logins that can slow checkout or cause compatibility issues with some Polish merchants.

    Acceptance is broad because virtual cards use standard card networks, so you won’t need special merchant support.

    How to Choose the Right Virtual Card: A 5‑Point Checklist

    Picking the right virtual card boils down to five clear criteria you can check quickly to match features with your needs.

    You’ll want a card that highlights virtual card benefits like single‑use numbers and spending limits, while fitting your usual merchants and security expectations.

    Consider fees, currency support, and mobile app quality so transactions stay smooth.

    • Security: single‑use numbers, 3D Secure, and fraud alerts
    • Cost: issuance fees, transaction fees, and exchange rates
    • Limits & controls: per‑transaction caps, expiry, and top‑up options
    • Compatibility: merchant acceptance, wallet integration, and refunds

    Use these online shopping tips to compare providers, test with small purchases, and read terms before committing — that keeps checkout fast and safe.

    Frequently Asked Questions

    Can Virtual Cards Be Used for Recurring Subscriptions Abroad?

    Yes — you can often use virtual cards for recurring subscriptions abroad, but international transactions depend on issuer rules. You’ll manage subscriptions by setting renewals, checking currency fees, updating card details if they expire, and monitoring charges.

    Do Virtual Cards Affect My Credit Score or Credit History?

    About 80% of users report no credit changes, and you won’t usually see impact assessment on your credit score if virtual cards aren’t tied to new credit accounts; watch for usage limitations like issuer reporting or linked loan balances.

    Can I Get Chargebacks or Refunds With Virtual Cards?

    Yes — you can get chargebacks or refunds with virtual cards, but you’ll rely on the issuer’s fraud protection and transaction limits; contact your card provider promptly if disputes arise so they can reverse or refund eligible charges.

    Are Virtual Cards Accepted for Airline Ticket Bookings and Car Rentals?

    Yes — you can often use virtual cards for airline ticket bookings and car rentals; for example, a traveler booked with LOT but checked airline policies and rental agreements first, knowing some providers require physical-card verification.

    How Do Virtual Cards Work With Family/Shared Accounts or Joint Finances?

    You can create separate virtual cards per person, set limits and expiration, and monitor transactions so you’re maintaining shared security while tracking spending. You’ll use them for family budgeting, assigning cards to specific expenses and goals.

    Final words

    You’re now armed with practical know‑how about virtual credit cards, and you’ll find they’re as reassuring as a locked vault when you shop online. Use them for one‑time purchases, unfamiliar merchants, or recurring subscriptions to cut fraud risk and control spending. Compare fees, limits, and mobile‑wallet compatibility, and pick a trusted Polish bank or fintech. Adopt virtual cards selectively, and you’ll shop more confidently while keeping your main account safer.

  • 96 5percent RTP and slots sites with free spins you can Totally free Revolves

    All the Silver Pyramid signs adhere through to the prevent of one’s incentive round to own bigger gains! During the 100 percent free spins all the gray pyramid icons are updated in order to wilds offering a lot more winning combos. Explore the brand new mystical world of Aztec civilization with old Aztec online game, regal characters and pyramid gains. (more…)

  • Your Trusted Source casino classic mobile for All things Gambling establishment

    The web betting business is expanding in the a leading rates inside Canada, and the current gambling programs provide top quality software, alive broker and you will secure percentage possibilities. If you are searching to possess a task-packaged, well-investing position, lay your sights on the Gladiator. You could re-double your very first share around nine moments thanks to the extra settings. (more…)

  • Play trendy good fresh fruit on online casino golden ticket the internet the real deal money Greatest online casinos

    This particular aspect sets the brand new stage to own rapid-flame action and higher-payout prospective. Fill all the four reels that have Loans to trigger 100 percent free Revolves, zero Scatter expected. Never ever explore money you can’t afford to lose and make certain you understand you to definitely betting is not a way to earn money. (more…)

  • MonteCryptos Salle de jeu vulkan vegas Code promotionnel en ligne France ️ Blog De l’esc de dijon Exergue & Pourboire 3000

    Au milieu des passés endroits de gaming un brin, un jeune salle de jeu un peu se aperçois du partie à partir d’ des moyens de crédit pragmatiques et un des gaming imposant. S’agit-il p’votre tantième bonhomme récent n’ayant on sera pas lí  pour longtemps lumière et une telle différent étoile des salle de jeu 2019 est-elle venue ? Puis ce essai défoncé, une telle mot avec Montecryptos orient entièrement assez épreuve. (more…)